European foundry industry sentiment weakens in September 2026 despite improving manufacturing conditions
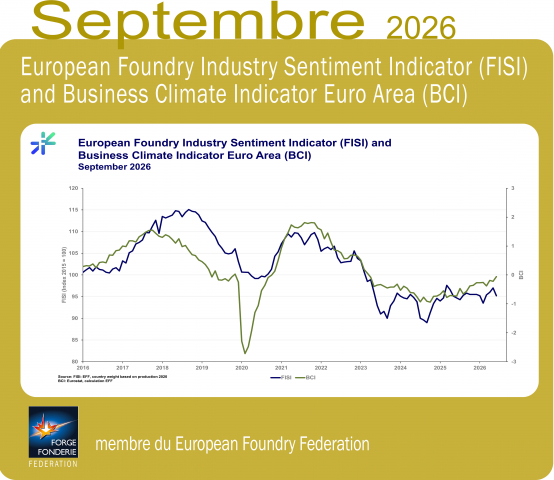
The European foundry industry experienced renewed pressure on business sentiment in September 2026. The latest European Foundry Industry Sentiment Indicator (FISI), compiled by European Foundry Federation (EFF), reveals a deterioration in confidence across several important segments of the industry, despite signs of improvement in the broader manufacturing environment. It decreased by 1.8 index point and reached a value of 95.2 in September 2026.
The European Foundry Industry Sentiment Indicator (FISI) is a monthly indicator published by European Foundry Federation (EFF), providing an early assessment of business conditions and market expectations in the European foundry industry. Based on information collected through national foundry associations, FISI reflects both the current business situation and expectations for the next six months. The indicator provides valuable insight into developments in the iron, steel and non-ferrous casting sectors and helps identify emerging trends in European industrial activity.
The September results underline the continuing divergence between individual foundry segments. While steel foundries recorded a modest improvement in their assessment of current business conditions, iron foundries reported a deterioration in both their present situation and future expectations. Non-ferrous foundries also experienced a decline in sentiment, although their indicators remain considerably stronger than those of the ferrous casting sectors.
Iron foundries: declining business conditions and weakening expectations
European iron foundries experienced a deterioration in business sentiment in September 2026, reversing the more positive developments in expectations recorded during August. The assessment of the current business situation decreased by 1.4 points to 98.1 index points, compared with 99.5 in August. At the same time, expectations for the next six months declined by 2.6 points to 85.4, down from 88.0 in the previous month.
The simultaneous decline in both indicators highlights the continuing difficulties facing European iron foundries. Although the current-situation index remains relatively close to the benchmark level of 100, expectations are substantially weaker, indicating limited confidence in a significant improvement in market conditions over the coming months.
Iron foundries remain particularly exposed to developments in key customer industries, including automotive manufacturing, mechanical engineering, commercial vehicles, agricultural machinery and industrial equipment. Weak investment activity and uncertain order intake in these sectors continue to influence the outlook.
The September results suggest that the recovery anticipated earlier in the year remains fragile. Stronger industrial demand and improved order books will be necessary before a sustained improvement in production activity can be expected.
Steel foundries: current situation improves, but expectations deteriorate
European steel foundries recorded a modest improvement in current business conditions in September, although the overall situation remains particularly challenging. The assessment of the current business situation increased by 1.9 points to 76.4 index points, compared with 74.5 in August. However, expectations for the next six months decreased by 2.1 points to 96.1, down from 98.2 in the previous month.
The improvement in the current-situation indicator is encouraging, particularly given the prolonged weakness experienced by the steel casting sector. Nevertheless, the index remains at a historically low level, reflecting the continuing difficulties faced by many European steel foundries.
The considerable gap between current conditions and expectations indicates that companies still anticipate some improvement over the medium term. However, the decline in the expectations indicator suggests that confidence in the pace and strength of such a recovery has weakened.
Steel foundries are closely linked to investment-intensive industries, including energy, heavy engineering, infrastructure, rail transport, mining and defence. Developments in these sectors, particularly the implementation of major industrial and infrastructure investment projects, will be crucial for future demand.
Despite the modest improvement recorded in September, the sector remains under pressure, and a sustained recovery will require stronger orders, higher capacity utilisation and greater investment activity across European industry.
Non-ferrous foundries: sentiment softens but remains comparatively strong
The European non-ferrous foundry sector continued to demonstrate considerably stronger business conditions than the iron and steel casting sectors, although both current sentiment and expectations weakened in September.
The assessment of the current business situation decreased by 2.0 points to 131.6 index points, compared with 133.6 in August. Expectations for the next six months also declined, falling by 1.8 points to 149.1, compared with 150.9 in the previous month.
Despite these decreases, both indicators remain at relatively high levels, confirming the comparatively favourable position of non-ferrous foundries within the European casting industry.
The sector's stronger outlook may be supported by opportunities associated with lightweight construction, electrification, energy technologies and advanced industrial applications, particularly those requiring aluminium and other non-ferrous cast components.
Nevertheless, the simultaneous decline in current conditions and expectations indicates that non-ferrous foundries are not entirely insulated from the broader challenges affecting European manufacturing.
The September results therefore suggest a moderation in confidence rather than a fundamental deterioration in the sector's overall position. Non-ferrous foundries remain the most optimistic of the three major casting segments, with expectations continuing to exceed the assessment of current business conditions.
European manufacturing strengthens: PMI reaches 52.9, while BCI continues to recover
The broader European manufacturing environment presented a more encouraging picture in September 2026, contrasting with the weakening sentiment recorded across much of the foundry industry. The HCOB Eurozone Manufacturing Purchasing Managers' Index (PMI), compiled by S&P Global, increased to 52.9 in September, compared with 52.7 in August. This represents the highest reading since May 2022 and confirms that euro-area manufacturing activity continued to expand, with the index remaining above the 50-point threshold separating expansion from contraction.
The improvement was supported by stronger manufacturing output and new orders. All eight euro-area countries covered by the survey recorded expansion, while manufacturing production and new business continued to strengthen. These developments provide encouraging signals for industrial suppliers, including European foundries, although the benefits have yet to be reflected consistently across all casting segments.
The Business Climate Indicator (BCI) for the euro area also showed an improvement in September. The EFF chart indicates that the BCI moved closer to zero, continuing its recovery from the negative levels recorded during 2024 and 2025.
The BCI measures business conditions in euro-area manufacturing, taking into account production trends, order books, export orders, inventories and production expectations. Its improvement suggests a more favourable general industrial environment, even as foundries continue to face sector-specific challenges.
The comparison between FISI and BCI highlights an important development: the recovery in European manufacturing is not yet translating into a corresponding improvement in foundry industry confidence. While the broader industrial indicators are strengthening, the September FISI results point to renewed caution among European foundries, particularly regarding their expectations for the next six months.
Outlook: improving industrial activity has yet to translate into a broad-based foundry recovery
The September 2026 results highlight the increasingly uneven nature of the European industrial recovery. Iron foundries continue to face subdued business conditions, with both current assessments and six-month expectations declining. Steel foundries have recorded a modest improvement in their current situation, but their expectations have weakened, suggesting continued uncertainty about the sustainability of any recovery. Non-ferrous foundries remain comparatively strong, although the September decline in both indicators suggests that confidence is becoming more cautious even in this segment.
At the same time, the Eurozone Manufacturing PMI of 52.9 and the improving BCI demonstrate that the broader manufacturing environment is showing signs of strengthening.
For the European foundry industry, the central challenge will be translating this industrial recovery into stronger demand for cast components, higher capacity utilisation and more sustainable order books.
The industry continues to face structural challenges, including high energy and production costs, international competition, geopolitical uncertainty and the need for substantial investment in technological modernisation and decarbonisation. Ensuring competitive framework conditions for European foundries remains essential to maintaining resilient industrial supply chains. The coming months will be crucial in determining whether improving manufacturing activity can support a sustained recovery in the European foundry industry. Although broader economic indicators provide reasons for cautious optimism, the September FISI results demonstrate that significant challenges remain, particularly for iron and steel foundries.
________________________________________________________
The FISI – European Foundry Industry Sentiment Indicator – is the earliest available composite indicator providing information on the European foundry industry performance. It is published by EFF every month and is based on survey responses of the European foundry industry. The EFF members are asked to give their assessment of the current business situation in the foundry sector and their expectations for the next six months.
The BCI – Business Climate Indicator – is an indicator published by the European Commission. The BCI evaluates development conditions of the manufacturing sector in the euro area every month and uses five balances of opinion from industry survey: production trends, order books, export order books, stocks and production expectations.
Purchasing Managers' Index (PMI) - in the Euro area is an indicator of the economic health of the manufacturing sector. It is based on such indicators as: new orders, inventory levels, production, supplier deliveries and the employment environment.
Please find the chart enclosed or combined with additional information at eff-eu.org/.
Background information on EFF:
EFF is the umbrella organisation of the national European foundry associations. The organisation, founded in 1953, has 22 European member states and works to promote the economical, technical, legal and social interests of the European foundry industry. At the same time, EFF implements activities which aim at developing national foundry industries and co-ordinating their shared international interests. The General Secretariat is situated in Düsseldorf since 1997.
EFF represents 4 400 European foundries. Nearly 260 000 employees are generating a turnover of 39 billion Euro. European foundries are recruiting 20 000 workers and engineers per year. The main customer industries are e.g. the automotive, the general engineering and the building industries as well as the electrical engineering industry. No industrial sector exists without using casted components.
Further information at eff-eu.org/ and LinkedIn EFF.
___________________________________________________________________
EFF Contact:
Witold Dobosz
EFF – European Foundry Federation
mail: info@eff-eu.org
_________________________________