European Foundry Industry Sentiment improves in August 2026 – expectations strengthen, but major differences between foundry segments remain.
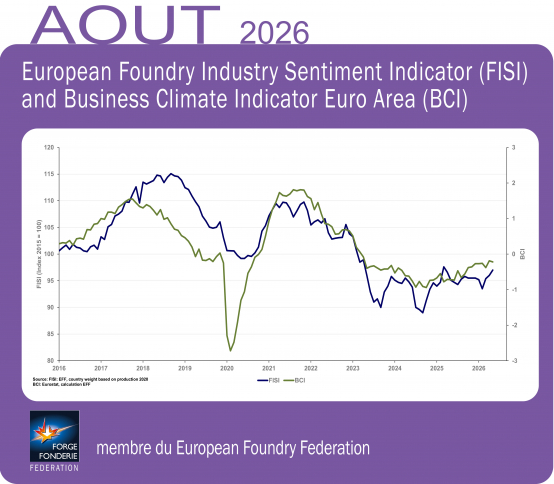
The European foundry industry recorded a further improvement in business sentiment in August 2026. The European Foundry Industry Sentiment Indicator (FISI) increased to 97.0 points, up from 96.0 in July, continuing the gradual recovery seen after the weakness earlier this year. Nevertheless, FISI remains below the benchmark level of 100, underlining that the recovery of the European foundry industry is still incomplete and highly uneven across individual casting segments. The August data show a particularly strong contrast between steel foundries, which continue to face difficult current conditions, and the much stronger non-ferrous sector.
The FISI is the earliest available composite indicator providing information on the performance of the European foundry industry. It is published monthly by EFF - European Foundry Federation and is based on survey responses from the European foundry industry. EFF members assess both the current business situation and their expectations for the next six months.
European manufacturing environment continues to improve
The August FISI results should be viewed against a more encouraging manufacturing environment. European manufacturing also strengthened during August. The final Eurozone Manufacturing PMI reached 52.7, up from 51.9 in July and its highest level since May 2022. The improvement was supported by stronger manufacturing activity in Germany, although conditions remained uneven across individual European economies.
The Business Climate Indicator (BCI) for the euro area stood at -0.22 in August, compared with -0.19 in July. Although it therefore remains in negative territory, the longer-term chart shows that the business climate has recovered considerably from the lows recorded in 2024. The BCI is published by the European Commission and assesses conditions in euro-area manufacturing based on production trends, order books, export order books, stocks and production expectations.
Taken together, FISI at 97.0, BCI at -0.22 and European Manufacturing PMI at 52.7 present a mixed but gradually improving picture. Manufacturing activity is expanding, while confidence in the European foundry industry is recovering more slowly and remains below its benchmark level.
Iron foundries: current conditions soften, but expectations rebound
The situation of European iron foundries remained mixed in August. The assessment of the current business situation decreased by 0.5 points to 99.5 index points, bringing it just below the benchmark level of 100.
At the same time, however, expectations improved significantly. The index measuring expectations for the next six months increased by 2.7 points to 88.0.
This represents a notable change compared with July, when the current-situation indicator had improved to 100.0 while six-month expectations declined to 85.3. The August results therefore suggest that, although current market conditions have softened slightly, iron foundries have become more confident about the months ahead.
Nevertheless, expectations remain well below 100. This indicates continued caution regarding future order intake and demand from important customer industries. Iron foundries remain particularly exposed to developments in automotive production, mechanical engineering, commercial vehicles, agricultural machinery and other industrial sectors.
The August increase in expectations is encouraging, but a sustainable recovery will ultimately depend on stronger orders and higher production volumes across European manufacturing.
Steel foundries: current situation remains very weak, but expectations improve
European steel foundries continue to report the most difficult current conditions among the three major foundry segments. In August, the assessment of the current business situation increased slightly by 0.2 points to 74.5 index points. At the same time, expectations for the next six months increased by 0.6 points to 98.2.
The substantial gap between the current-situation index of 74.5 and expectations of 98.2 is particularly significant. It shows that steel foundries remain under considerable pressure today, but companies expect conditions to improve over the coming six months.
The July figures already showed this contrast, with current conditions at only 74.3 and expectations at 97.6. The August improvement in both indicators is therefore positive, although the extremely low current-situation reading confirms that a meaningful recovery in actual business activity has yet to materialize.
Steel foundries remain dependent on investment-intensive sectors such as heavy machinery, energy, mining, rail, infrastructure and defence. Stronger capital investment and industrial orders will therefore be essential if improved expectations are to translate into higher capacity utilisation and production.
Non-ferrous foundries remain the strongest segment
The picture is substantially more positive for European non-ferrous foundries. In August 2026, the assessment of the current business situation increased by 0.4 points to 133.6 index points. Expectations for the next six months strengthened even more, rising by 1.9 points to 150.9.
Both indicators are not only well above the benchmark level but also considerably stronger than those recorded in the iron and steel casting segments. In July, the current-situation indicator stood at 133.2 and expectations at 149.0, meaning that the sector strengthened further in August.
Non-ferrous foundries therefore remain the strongest part of the European foundry industry. The segment continues to benefit from demand connected with lightweight components, electrification, energy technologies and advanced industrial applications.
The particularly high six-month expectations reading of 150.9 indicates strong confidence compared with the ferrous casting sectors and suggests that non-ferrous foundries expect favourable market conditions to continue.
Outlook: recovery is becoming more visible, but remains uneven
The August results provide grounds for cautious optimism. Overall FISI increased from 96.0 to 97.0, while global manufacturing activity remained firmly in expansion territory with a PMI of 52.3. Eurozone manufacturing strengthened further, reaching a PMI of 52.7. At the same time, the BCI remained negative at -0.22, demonstrating that the broader European industrial environment is not yet free of uncertainty.
The differences between individual foundry segments remain striking. Iron foundries are close to the benchmark level in their assessment of current conditions, but their expectations remain subdued. Steel foundries continue to experience particularly weak current business conditions, despite substantially stronger expectations for the coming six months. Non-ferrous foundries, by contrast, report both strong current conditions and very positive expectations.
For European foundries, the key question is now whether improving manufacturing activity and stronger expectations will translate into higher order intake, increased capacity utilisation and stronger investment by customer industries.
The industry continues to face significant structural challenges, including high energy and production costs, geopolitical uncertainty, global competition and uneven demand from key customer sectors. EFF has also highlighted competitiveness issues related to the EU's Carbon Border Adjustment Mechanism (CBAM), particularly the risk that European foundries face higher costs for imported raw materials while many imported finished foundry products remain outside the mechanism's scope.
European foundries are strategic suppliers to the automotive, machinery, energy, railway, aerospace, defence, construction and infrastructure sectors. Maintaining a competitive European foundry industry is therefore essential not only for foundry companies themselves, but also for resilient European industrial supply chains and Europe's long-term industrial competitiveness.
EFF – European Foundry Federation will continue to monitor developments through its monthly European Foundry Industry Sentiment Indicator (FISI), providing market intelligence on current conditions and expectations across the European foundry industry.
The FISI – European Foundry Industry Sentiment Indicator – is the earliest available composite indicator providing information on the European foundry industry performance. It is published by EFF every month and is based on survey responses of the European foundry industry. The EFF members are asked to give their assessment of the current business situation in the foundry sector and their expectations for the next six months.
The BCI – Business Climate Indicator – is an indicator published by the European Commission. The BCI evaluates development conditions of the manufacturing sector in the euro area every month and uses five balances of opinion from industry survey: production trends, order books, export order books, stocks and production expectations.
Purchasing Managers' Index (PMI) - in the Euro area is an indicator of the economic health of the manufacturing sector. It is based on such indicators as: new orders, inventory levels, production, supplier deliveries and the employment environment.
Please find the chart enclosed or combined with additional information at eff-eu.org/.
Background information on EFF:
EFF is the umbrella organisation of the national European foundry associations. The organisation, founded in 1953, has 22 European member states and works to promote the economical, technical, legal and social interests of the European foundry industry. At the same time, EFF implements activities which aim at developing national foundry industries and co-ordinating their shared international interests.
EFF represents 4 400 European foundries. Nearly 260 000 employees are generating a turnover of 39 billion Euro. European foundries are recruiting 20 000 workers and engineers per year. The main customer industries are e.g. the automotive, the general engineering and the building industries as well as the electrical engineering industry. No industrial sector exists without using casted components.
Further information at eff-eu.org/ and LinkedIn EFF.
___________________________________________________________________
EFF • European Foundry Federation
Alameda Urquijo 33, 1D, Abando 48008, Bilbao • Spain
info@eff-eu.org
Contact: info@eff-eu.org • eff-eu.org/ • LinkedIn EFF
7/7
EFF Contact:
Witold Dobosz
EFF – European Foundry Federation
mail: info@eff-eu.org
________________________________________