Back To Top
Plateforme adhérents
ENG
News
Accueil > News > Climat des affaires dans l’industrie européenne de la fonderie en août 2026
Climat des affaires dans l’industrie européenne de la fonderie en août 2026
29 September 2026
Partager | Imprimer

L’indice FISI (Foundry Industry Sentiment Indicator) est publié chaque mois par l’association européenne de fonderie EFF à partir des réponses des organisations membres, dont pour la France, la Fédération Forge Fonderie, sur le climat des affaires dans le secteur de la fonderie (fonte, acier et non-ferreux) à date et leurs attentes pour les six prochains mois.
Télécharger les résultats de l’indice FISI d’août 2026  ICI

L’indice de confiance des fonderies en Europe s'améliore en août 2026 mais des différences importantes persistent entre les différents segments de la fonderie.

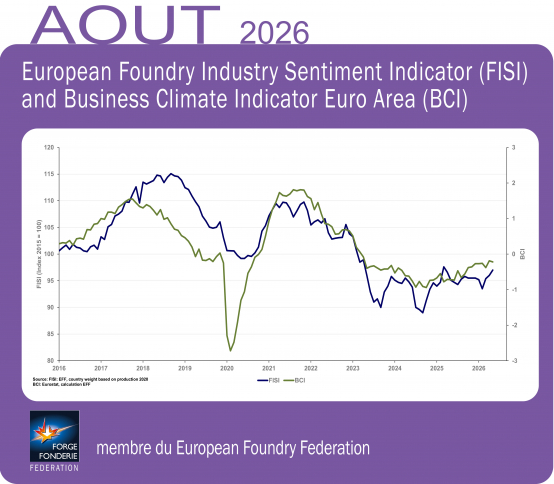
Le secteur européen de la fonderie a enregistré une nouvelle amélioration du climat des affaires en août 2026. L’indice FISI a progressé à 97,0 points, contre 96,0 en juillet, poursuivant ainsi la reprise progressive observée après la baisse enregistrée en début d’année. Néanmoins, il reste en dessous du seuil de référence de 100, ce qui souligne que la reprise de l'industrie européenne de la fonderie est encore incomplète et très inégale selon les segments de la fonderie. Les données du mois d'août montrent un contraste particulièrement marqué entre les fonderies d'acier, qui continuent de faire face à des conditions difficiles, et le secteur des métaux non ferreux, nettement plus solide.

Ces résultats doivent être replacés dans le contexte d'un environnement plus encourageant pour l'industrie manufacturière. L'indice des directeurs d'achat PMI (**) définitif de la zone euro a atteint 52,7, en hausse par rapport aux 51,9 enregistrés en juillet, et a ainsi atteint son plus haut niveau depuis mai 2022. Cette amélioration a été soutenue par une activité manufacturière plus soutenue en Allemagne, même si la situation est restée inégale d'une économie européenne à l'autre.

L'indice BCI (*) de la zone euro s'est établi à -0,22 en août, contre -0,19 en juillet. Bien qu'il reste donc en territoire négatif, le graphique à long terme montre que le climat des affaires s'est considérablement redressé par rapport aux plus bas niveaux enregistrés en 2024.

Pris dans leur ensemble, ces trois indices, le FISI à 97,0, le BCI à -0,22 et l’indice PMI à 52,7, présentent un tableau mitigé mais en amélioration progressive. L’activité manufacturière est en expansion, tandis que la confiance dans le secteur européen de la fonderie se redresse plus lentement et reste inférieure à son niveau de référence.


Fonderies de fonte : les conditions actuelles s'affaiblissent, mais les prévisions remontent

La situation des fonderies de fonte européennes est restée contrastée en août. L'évaluation de la conjoncture actuelle a reculé de 0,5 point pour s'établir à 99,5 points d'indice, se situant ainsi juste en dessous du seuil de référence de 100. Dans le même temps, les prévisions se sont toutefois nettement améliorées. L'indice mesurant les prévisions pour les six prochains mois a progressé de 2,7 points pour atteindre 88,0.

Cela représente un changement notable par rapport au mois de juillet, où l’indicateur de la situation actuelle s’était amélioré pour atteindre 100,0 tandis que les prévisions à six mois avaient reculé à 85,3. Les résultats du mois d’août suggèrent donc que, bien que les conditions actuelles du marché se soient légèrement affaiblies, les fonderies de fonte sont désormais plus confiantes quant aux mois à venir.

Néanmoins, les prévisions restent bien en deçà de 100. Cela témoigne d’une prudence persistante quant aux futures prises de commandes et à la demande émanant des principaux secteurs clients. Les fonderies de fonte restent particulièrement exposées à l’évolution de la production automobile, de la construction mécanique, des véhicules utilitaires, des machines agricoles et d’autres secteurs industriels.

La hausse des prévisions enregistrée en août est encourageante, mais une reprise durable dépendra en fin de compte d’une augmentation des commandes et des volumes de production dans l’ensemble de l’industrie manufacturière européenne.


Fonderies d'acier : la situation actuelle reste très morose, mais les perspectives s'améliorent

Les fonderies d'acier européennes continuent de faire état des conditions actuelles les plus difficiles parmi les trois principaux segments de la fonderie. En août, l'évaluation de la situation économique actuelle a légèrement progressé de 0,2 point pour atteindre 74,5 points d'indice. Dans le même temps, les prévisions pour les six prochains mois ont augmenté de 0,6 point pour s'établir à 98,2.

L'écart considérable entre l'indice de la situation actuelle (74,5) et celui des prévisions (98,2) est particulièrement significatif. Il montre que les fonderies d'acier restent aujourd'hui soumises à une pression considérable, mais que les entreprises s'attendent à une amélioration de la situation au cours des six prochains mois.

Les chiffres de juillet reflétaient déjà ce contraste, avec un indice de la situation actuelle à seulement 74,3 et celui des prévisions à 97,6. L’amélioration observée en août pour ces deux indicateurs est donc positive, même si le niveau extrêmement bas de l’indice de la situation actuelle confirme qu’une reprise significative de l’activité économique réelle ne s’est pas encore concrétisée.

Les fonderies d’acier restent tributaires de secteurs à forte intensité d’investissement tels que la mécanique lourde, l’énergie, l’exploitation minière, le secteur ferroviaire, les infrastructures et la défense. Une hausse des investissements en capital et des commandes industrielles sera donc essentielle pour que l’amélioration des prévisions se traduise par une meilleure utilisation des capacités et une augmentation de la production.


Les fonderies de métaux non ferreux restent le segment le plus dynamique

La situation est nettement plus favorable pour les fonderies européennes de métaux non ferreux. En août 2026, l’évaluation de la situation économique actuelle a progressé de 0,4 point pour atteindre 133,6 points d’indice. Les prévisions pour les six prochains mois se sont encore renforcées, gagnant 1,9 point pour s’établir à 150,9.

Ces deux indicateurs se situent non seulement bien au-dessus du niveau de référence, mais sont également nettement supérieurs à ceux enregistrés dans les autres segments. En juillet, l’indicateur de la situation actuelle s’établissait à 133,2 et celui des prévisions à 149,0, ce qui signifie que le secteur s’est encore renforcé en août.

Les fonderies de métaux non ferreux restent donc le pilier le plus solide de l’industrie européenne de la fonderie. Ce segment continue de bénéficier de la demande liée aux composants légers, à l’électrification, aux technologies énergétiques et aux applications industrielles de pointe.

Le niveau particulièrement élevé des prévisions à six mois, à 150,9, témoigne d’une forte confiance par rapport aux secteurs de la fonderie de métaux ferreux et suggère que les fonderies de métaux non ferreux s’attendent à ce que les conditions de marché favorables se maintiennent.


Perspectives : la reprise se confirme, mais reste inégale

Les résultats du mois d'août incitent à un optimisme prudent. L'indice FISI global est passé de 96,0 à 97,0, tandis que l'activité manufacturière mondiale est restée fermement en phase d'expansion avec un indice PMI à 52,7. Dans le même temps, le BCI est resté négatif à -0,22, ce qui montre que le contexte industriel européen dans son ensemble n'est pas encore exempt d'incertitudes.

Les différences entre les différents segments de la fonderie restent frappantes. Les fonderies de fonte se situent près du niveau de référence dans leur évaluation de la situation actuelle, mais leurs prévisions restent modérées. Les fonderies d'acier continuent de connaître une conjoncture particulièrement morose, malgré des prévisions nettement plus optimistes pour les six prochains mois. Les fonderies de métaux non ferreux, en revanche, font état à la fois d'une situation actuelle favorable et de prévisions très positives.


Source : Traduction du communiqué EFF (https://eff-eu.org/european-foundry-industry-sentiment-82/).

(*) Indice BCI : Business Climate Indicator. Indice de l’évolution du secteur manufacturier en zone euro publié par la Commission européenne à partir d’enquêtes sectorielles (tendances de la production ; carnets de commandes ; carnets de commandes à l'exportation ; stocks ; attentes en matière de production). Valeur égale à 0 : Situation neutre, ni optimisme ni pessimisme marqué.

(**) L'indice des directeurs d'achat (PMI) dans la zone euro est un indicateur de la santé économique du secteur manufacturier. Il est basé sur des indicateurs tels que les nouvelles commandes, les niveaux de stocks, la production, les livraisons des fournisseurs et l'environnement de l'emploi.


News
September 29 2026

European Foundry Industry Sentiment improves in August 2026

European Foundry Industry Sentiment improves in August 2026 – expectations strengthen, but major differences between foundry segments remain.
The European foundry industry recorded a further improvement in business sentiment in August 2026. The European Foundry Industry Sentiment Indicator (FISI) increased to 97.0 points, up from 96.0 in July, continuing the gradual recovery seen after the weakness earlier this year. Nevertheless, FISI remains below the benchmark level of 100, underlining that the recovery of the European foundry industry is still incomplete and highly uneven across individual casting segments. The August data show a particularly strong contrast between steel foundries, which continue to face difficult current conditions, and the much stronger non-ferrous sector.

The FISI is the earliest available composite indicator providing information on the performance of the European foundry industry. It is published monthly by EFF - European Foundry Federation and is based on survey responses from the European foundry industry. EFF members assess both the current business situation and their expectations for the next six months.
European manufacturing environment continues to improve
The August FISI results should be viewed against a more encouraging manufacturing environment. European manufacturing also strengthened during August. The final Eurozone Manufacturing PMI reached 52.7, up from 51.9 in July and its highest level since May 2022. The improvement was supported by stronger manufacturing activity in Germany, although conditions remained uneven across individual European economies.
The Business Climate Indicator (BCI) for the euro area stood at -0.22 in August, compared with -0.19 in July. Although it therefore remains in negative territory, the longer-term chart shows that the business climate has recovered considerably from the lows recorded in 2024. The BCI is published by the European Commission and assesses conditions in euro-area manufacturing based on production trends, order books, export order books, stocks and production expectations.
Taken together, FISI at 97.0, BCI at -0.22 and European Manufacturing PMI at 52.7 present a mixed but gradually improving picture. Manufacturing activity is expanding, while confidence in the European foundry industry is recovering more slowly and remains below its benchmark level.


Iron foundries: current conditions soften, but expectations rebound
The situation of European iron foundries remained mixed in August. The assessment of the current business situation decreased by 0.5 points to 99.5 index points, bringing it just below the benchmark level of 100.
At the same time, however, expectations improved significantly. The index measuring expectations for the next six months increased by 2.7 points to 88.0.
This represents a notable change compared with July, when the current-situation indicator had improved to 100.0 while six-month expectations declined to 85.3. The August results therefore suggest that, although current market conditions have softened slightly, iron foundries have become more confident about the months ahead.
Nevertheless, expectations remain well below 100. This indicates continued caution regarding future order intake and demand from important customer industries. Iron foundries remain particularly exposed to developments in automotive production, mechanical engineering, commercial vehicles, agricultural machinery and other industrial sectors.
The August increase in expectations is encouraging, but a sustainable recovery will ultimately depend on stronger orders and higher production volumes across European manufacturing.


Steel foundries: current situation remains very weak, but expectations improve
European steel foundries continue to report the most difficult current conditions among the three major foundry segments. In August, the assessment of the current business situation increased slightly by 0.2 points to 74.5 index points. At the same time, expectations for the next six months increased by 0.6 points to 98.2.
The substantial gap between the current-situation index of 74.5 and expectations of 98.2 is particularly significant. It shows that steel foundries remain under considerable pressure today, but companies expect conditions to improve over the coming six months.
The July figures already showed this contrast, with current conditions at only 74.3 and expectations at 97.6. The August improvement in both indicators is therefore positive, although the extremely low current-situation reading confirms that a meaningful recovery in actual business activity has yet to materialize.
Steel foundries remain dependent on investment-intensive sectors such as heavy machinery, energy, mining, rail, infrastructure and defence. Stronger capital investment and industrial orders will therefore be essential if improved expectations are to translate into higher capacity utilisation and production.


Non-ferrous foundries remain the strongest segment
The picture is substantially more positive for European non-ferrous foundries. In August 2026, the assessment of the current business situation increased by 0.4 points to 133.6 index points. Expectations for the next six months strengthened even more, rising by 1.9 points to 150.9.
Both indicators are not only well above the benchmark level but also considerably stronger than those recorded in the iron and steel casting segments. In July, the current-situation indicator stood at 133.2 and expectations at 149.0, meaning that the sector strengthened further in August.
Non-ferrous foundries therefore remain the strongest part of the European foundry industry. The segment continues to benefit from demand connected with lightweight components, electrification, energy technologies and advanced industrial applications.
The particularly high six-month expectations reading of 150.9 indicates strong confidence compared with the ferrous casting sectors and suggests that non-ferrous foundries expect favourable market conditions to continue.
Outlook: recovery is becoming more visible, but remains uneven
The August results provide grounds for cautious optimism. Overall FISI increased from 96.0 to 97.0, while global manufacturing activity remained firmly in expansion territory with a PMI of 52.3. Eurozone manufacturing strengthened further, reaching a PMI of 52.7. At the same time, the BCI remained negative at -0.22, demonstrating that the broader European industrial environment is not yet free of uncertainty.
The differences between individual foundry segments remain striking. Iron foundries are close to the benchmark level in their assessment of current conditions, but their expectations remain subdued. Steel foundries continue to experience particularly weak current business conditions, despite substantially stronger expectations for the coming six months. Non-ferrous foundries, by contrast, report both strong current conditions and very positive expectations.


For European foundries, the key question is now whether improving manufacturing activity and stronger expectations will translate into higher order intake, increased capacity utilisation and stronger investment by customer industries.
The industry continues to face significant structural challenges, including high energy and production costs, geopolitical uncertainty, global competition and uneven demand from key customer sectors. EFF has also highlighted competitiveness issues related to the EU's Carbon Border Adjustment Mechanism (CBAM), particularly the risk that European foundries face higher costs for imported raw materials while many imported finished foundry products remain outside the mechanism's scope.
European foundries are strategic suppliers to the automotive, machinery, energy, railway, aerospace, defence, construction and infrastructure sectors. Maintaining a competitive European foundry industry is therefore essential not only for foundry companies themselves, but also for resilient European industrial supply chains and Europe's long-term industrial competitiveness.
EFF – European Foundry Federation will continue to monitor developments through its monthly European Foundry Industry Sentiment Indicator (FISI), providing market intelligence on current conditions and expectations across the European foundry industry.
 

The FISI – European Foundry Industry Sentiment Indicator – is the earliest available composite indicator providing information on the European foundry industry performance. It is published by EFF every month and is based on survey responses of the European foundry industry. The EFF members are asked to give their assessment of the current business situation in the foundry sector and their expectations for the next six months.
The BCI – Business Climate Indicator – is an indicator published by the European Commission. The BCI evaluates development conditions of the manufacturing sector in the euro area every month and uses five balances of opinion from industry survey: production trends, order books, export order books, stocks and production expectations.
Purchasing Managers' Index (PMI) - in the Euro area is an indicator of the economic health of the manufacturing sector. It is based on such indicators as: new orders, inventory levels, production, supplier deliveries and the employment environment.
Please find the chart enclosed or combined with additional information at eff-eu.org/.
Background information on EFF:
EFF is the umbrella organisation of the national European foundry associations. The organisation, founded in 1953, has 22 European member states and works to promote the economical, technical, legal and social interests of the European foundry industry. At the same time, EFF implements activities which aim at developing national foundry industries and co-ordinating their shared international interests.
EFF represents 4 400 European foundries. Nearly 260 000 employees are generating a turnover of 39 billion Euro. European foundries are recruiting 20 000 workers and engineers per year. The main customer industries are e.g. the automotive, the general engineering and the building industries as well as the electrical engineering industry. No industrial sector exists without using casted components.
Further information at eff-eu.org/ and LinkedIn EFF.
___________________________________________________________________
EFF • European Foundry Federation
Alameda Urquijo 33, 1D, Abando 48008, Bilbao • Spain
info@eff-eu.org
Contact: info@eff-eu.org • eff-eu.org/ • LinkedIn EFF
7/7
EFF Contact:
Witold Dobosz
EFF – European Foundry Federation
mail: info@eff-eu.org
________________________________________

Read more
 
All news >
Directory
Forge Fonderie
Magazine
Indicators
Press Room
Join us
Contact

Fédération Forge Fonderie
Head office
45 rue Louis Blanc F-92400 Courbevoie
Write us
45 rue Louis Blanc CS 30080 92038 La Défense Cedex

Tel. +33 (0)1 43 34 76 30
Fax. +33 (0)1 43 34 76 31


Access map

The Fédération Forge Fonderie is the French professional organization of metal shaping industries through forging, casting, metal additive manufacturing and related machining.

© 2016 Fédération Forge Fonderie - Credits & legal notice